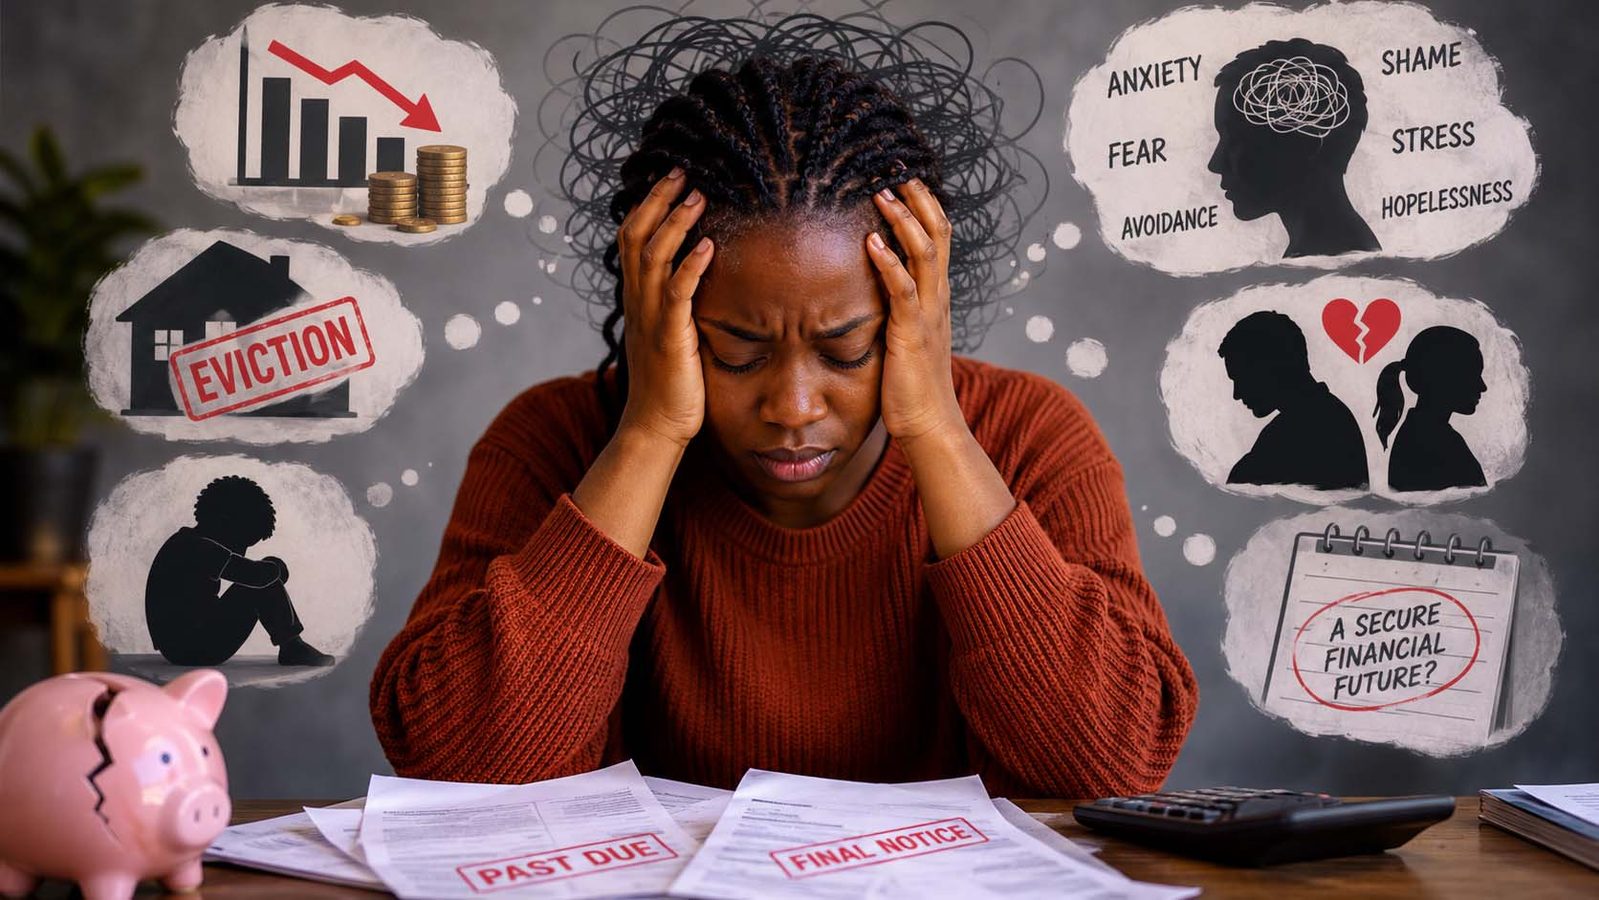
Financial trauma refers to the lasting psychological impact of severe or chronic financial hardship, poverty, debt crises, bankruptcy, eviction, sudden income loss or growing up in financial instability.
Like other forms of trauma, it can produce persistent patterns of thinking, feeling and behaving that continue to affect a person long after the original financial crisis has passed.
The concept of financial trauma has gained recognition among financial therapists and psychologists over the past decade, reflecting a growing understanding that the consequences of financial hardship are not simply material they reach deep into identity, relationships and neurological functioning.
What financial trauma looks like
Financial trauma manifests differently across individuals, but common presentations include:
Hypervigilance around money: Constant anxiety about finances even when objectively secure. Checking account balances compulsively, inability to spend money without severe anxiety or hoarding behaviours driven by fear of scarcity.
Avoidance and dissociation: The opposite pattern numbing to finances, avoiding looking at statements or bills, feeling paralysed when financial decisions arise. This mirrors avoidance patterns seen in other trauma responses.
Shame and secrecy: Deep shame about past financial circumstances, concealing financial history from partners or feeling fundamentally defective because of financial experiences.
Difficulty with financial planning: An inability to imagine a secure financial future, not a cognitive limitation but a trauma response where the future feels threatening or unreachable.
Relationship difficulties around money: Intense conflict with partners about finances, difficulty trusting others with financial information or choosing partners based on financial security in ways that override other important compatibility factors.
Who is affected
Financial trauma can affect anyone who has experienced severe financial hardship, but certain populations carry disproportionate burden:
People who grew up in poverty: Childhood financial instability is a particularly potent source of financial trauma, shaping money beliefs and behaviours in the nervous system during formative developmental periods. Research by Psychologist Pamela Elliott and Financial Therapist Amanda Clayman has documented how childhood financial experiences create lasting neurological and psychological patterns.
People who experienced sudden income loss: Job loss, business failure, divorce or medical debt can produce acute financial crisis that triggers trauma responses, particularly when the loss involved loss of identity, social status and security simultaneously.
Immigrants and refugees: Economic displacement and the financial precarity of immigration often involving remittance obligations, exploitation or work below one’s skill level carries specific financial trauma dimensions.
People who experienced financial abuse: Coercive control in intimate relationships frequently includes financial abuse, controlling access to money, sabotaging employment, creating debt in a partner’s name. This is both financial trauma and intimate partner violence trauma.
People navigating systemic financial exclusion: Discrimination, predatory lending, medical debt, student loan burden and other systemic financial harms produce financial trauma at the intersection of individual and structural harm.
Why it lasts
Financial trauma persists because of how trauma memory is encoded in the brain. Severe financial stressors, particularly those that threatened basic security can activate the brain’s threat system strongly enough to create conditioned responses.
Once the nervous system has learnt that financial uncertainty means danger, it responds to financial cues with alarm even when the objective danger is past. This is not irrational, it was adaptive. The problem is that the alarm system doesn’t automatically update when circumstances change.
This explains why people who grew up in poverty may continue to experience intense financial anxiety decades after achieving financial security and why survivors of financial abuse may respond with panic to benign financial situations that superficially resemble past threats.
Financial trauma is not weakness or poor financial education; it is a psychological response to real experiences of hardship and insecurity that can shape a person’s relationship with money for years or decades. It deserves the same recognition and treatment as other forms of trauma.
If your relationship with money is characterised by intense anxiety, avoidance, shame or distress that feels disproportionate to your current financial reality, financial trauma may be the lens that makes sense of it and the starting point for addressing it.


Leave a comment