
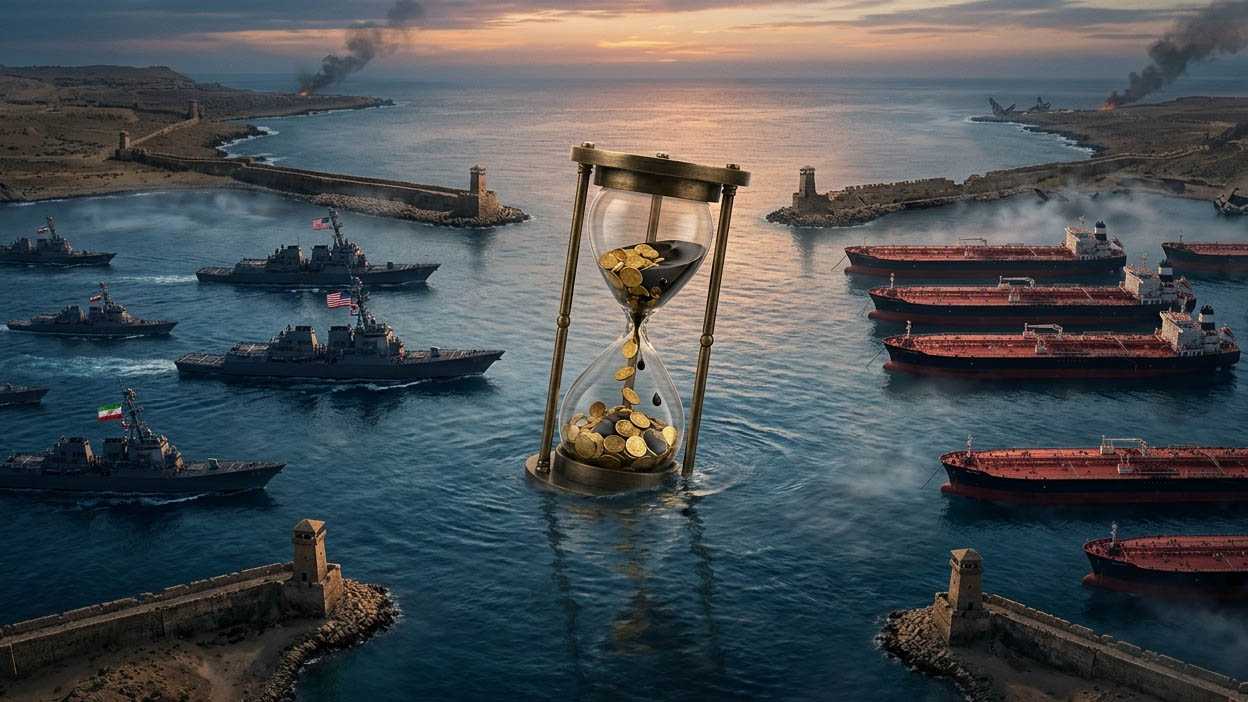
Though a fragile ceasefire has been in force for the past couple of weeks, a couple of facts remain; the Strait of Hormuz remains closed, both by the Americans and the Iranians and the negotiations have not yielded a positive outcome. Rhetoric from both sides continues to flood social media and indications are that a ceasefire is not on the horizon. Though the guns are a bit silent for now, the war is not over. The longer it lasts, the more the global economy remains under threat of inflation and energy deficiency.
Thus, inflation fears are becoming a reality and the price of oil remains under pressure. The price of brent crude has been elevated above the US$100 level for the past five days, signalling a higher future contract. Markets are strongly pricing in a deteriorating risk scenario. Furthermore, equity markets and commodities markets are flat lining over the past two weeks with marginal changes, but the two-week average or trend is a flat one, indicating a cautious or bearish stance in the market, which is largely associated with economies in recession, while earnings and economic data remain strong.
This paradox signals a global economy that is at a crossroads. It is, therefore, imperative that we understand all these dynamics and their impacts on daily life.The war has a direct impact on the price of all petroleum-related products, natural energy and fertiliser, among others. It is inevitable that we should brace for yet another fuel price increase. Last month, government was able to cushion the blow by releasing E334 million from the strategic oil purchasing fund to cover the cost difference between what you pay at the pump and the actual cost of supplying the product.
Given that the strategic fund had about E1.5 billion before the E334 million was drawn, leaving the current fund liquidity north of E1.1 billion. I would suppose that a higher intervention would be needed this time around, considering that news coming out of the petroleum companies suggests that the actual cost of sourcing the product is about the costs reflected in the price of brent crude oil.
Also, remember we cannot perpetually run this subsidy and at some point, the portion covered by government will eventually have to be factored into the open market price; the reversal will also have to be managed. It would be a manageable exit if the war were to end, say this month and damaged oil infrastructure in the Middle East were rapidly fixed. However, this process will take time and the price of oil may stay elevated for longer.
Hence, as we think about the looming hikes in energy prices, we must also be cognisant of the impact of the exit. If this war continues to drag on, the cushion will be depleted and there will be no option for a softer landing post to the crisis. Essentially, prices will rise very swiftly and steeply if the war continues into its third and fourth months. I say this because even if the war were to end today, government would still have to pump in some cost difference to ensure that the adjustment to pure market forces is contained at the current pump prices. This would require that we have enough in the strategic reserve fund to cover the cost until the price of brent crude climbs down to levels where the market clears at current prices. This may take a few months, some two to three months. Hence government needs to balance potential future implications and current pressing needs. In my view, to manage the situation, we need to allow for a full price change above the current prices, while maintaining the subsidy at current levels. This will draw down the fund north of E900 million. It is crucial that we have a two to three months exit contingency to ensure a softer landing upon exit.
Avoiding the full price effect this time around is tantamount to kicking the can down the road. Even if the war were to end today, we would still need another two to three months’ cushion to ensure that we do not see rapid increases. Hence, small full cost increases in between some cushioning phases as we manage the situation and monitor the situation.
I believe this time around, the producer and the consumer may have to shoulder the full cost. It is imperative, though, that we be forward looking and understand that funds in the stabilisation fund are not infinite but finite. Also, this will help manage inflation as prices will rise and yes, they will, but in a controlled environment and avoid rapid changes later on in the year.
Alternatively, we can bank on the hope that hostilities will end or a deal is struck in the next two weeks. Then, in that case, we would afford yet another subsidy and also be in a position to manage the exit. However, depleting the fund to zero makes us even more vulnerable, as we do not yet have strategic fuel reserves.


Leave a comment