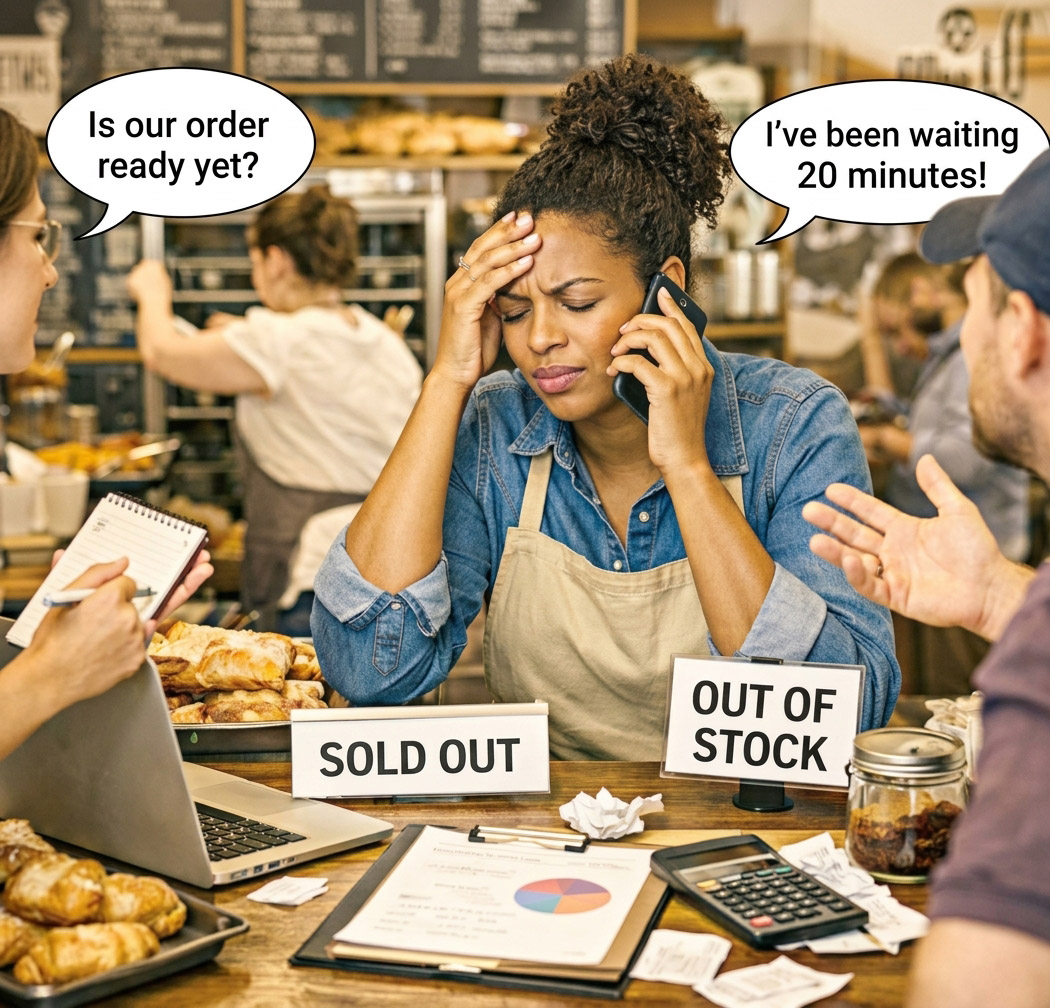
The busiest months of the year are closer than they feel. The rush that arrives in the final quarter is won long before it begins: In the stock ordered early, the suppliers lined-up and the shelves ready before demand climbs. The orders may come, but can your business meet them without stretching its cash too thin?
A loan can help fund that preparation, but borrowing makes sense only when the growth opportunity is clear and the repayments fit your business’s cash flow.
Start with the demand
Before seeking finance, estimate what customers are likely to buy and when. Review last year’s seasonal sales, current orders, customer enquiries and supplier lead times. Then calculate how much extra stock, labour, transport or equipment you will need—and when you’ll need to pay for it.
A useful financing plan connects each cost to a specific business need. For example, a confirmed order may require you to buy materials before the customer pays. In that case, short-term working capital or order finance may help bridge the gap. If you need machinery or vehicles to increase production or deliveries, asset finance may be a closer fit.
Check what the repayments will mean
More sales do not automatically mean more cash in the bank. Customers may pay late, suppliers may require deposits and unsold stock can tie up money after the busy period ends.
Build a cash flow forecast that includes the loan repayments, operating costs and expected customer payments. Ask whether the business could still manage if sales were lower than expected or payments arrived later than planned. If repayment depends on an unusually optimistic sales forecast, borrowing may add pressure instead of helping the business grow.
Consider whether borrowing is the right tool
A loan may be worth exploring when you have evidence of demand, a defined use for the funds and a realistic plan for repayment. You might also consider using retained earnings, negotiating supplier terms, requesting customer deposits or phasing your expansion. Each option affects cash flow differently.
Explore suitable business finance
In Eswatini, the Industrial Development Company of Eswatini (IDCE) lists products including SME loans, working capital, order finance, asset lease finance and corporate loans and equity. Its FAQ says funding is directed to registered businesses and sole traders; applicants should check the current product requirements and eligibility directly with IDCE.
The right question is not simply whether your business can borrow. It is whether the funding will help you meet a real opportunity, and whether the business can repay it under realistic conditions. Plan early, cost the opportunity carefully and choose finance that matches the need.