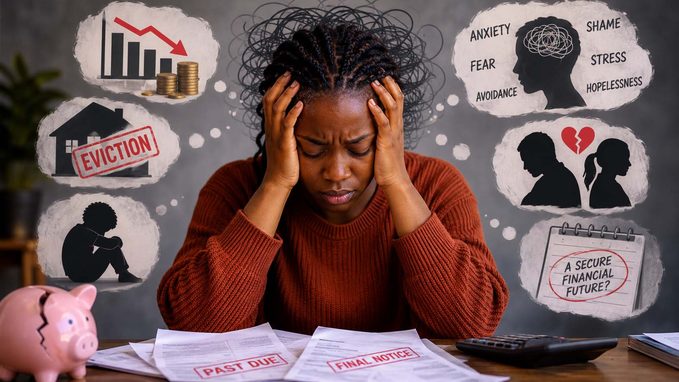
As the year draws to a close, many emaSwati are looking forward to the festive season, December salaries, bonuses, stokvel payouts and a well-deserved break. However, while there is excitement around festive celebrations and the opportunities that come with receiving extra money, this is also one of the most important times to take an honest look at your finances.
Before making plans for the new year, it is worth asking a few questions: How much did you earn this year? Where did your money go? Have you made progress towards your financial goals? More importantly, are you financially prepared for January?
A year-end financial review is not about counting your failures or feeling guilty about spending. It is about understanding your financial position, making necessary adjustments and ensuring that you do not carry avoidable financial pressure into another year.
Here is a practical checklist to help you finish the year on a stronger financial footing:
Review your spending habits and follow the money
Start by looking at your income and expenditure over the past 12 months. Go through your bank statements, mobile money transactions, debit orders and household expenses to establish where your money has been going.
Pay particular attention to recurring expenses such as groceries, electricity, transport, airtime, data, rent, school expenses and loan repayments.
You may discover that small, seemingly harmless purchases have accumulated into a substantial amount.
Takeaways, frequent online purchases, unused subscriptions and unplanned shopping can quietly eat into your income.
Give your December money a job
December can be financially deceptive. Between bonuses, stokvel payouts, savings withdrawals and festive spending, it can feel as though there is more money available than usual. However, remember that January comes with its own financial demands. School fees, uniforms, stationery, transport, groceries, rent and other bills do not wait for your finances to recover from Christmas.
Before spending your December income, allocate money towards these obligations. Separate essential expenses from festive spending and avoid treating your entire bonus or stokvel payout as disposable income.
If you receive a bonus, consider dividing it between savings, debt repayment, outstanding obligations and a reasonable amount for enjoyment.
Check your debt and borrowing commitments
Take stock of all your outstanding debts, including personal loans, vehicle finance, credit facilities, store accounts and money borrowed from individuals.
Write down the outstanding balances, interest rates and monthly instalments.
This will help you understand how much of your income is already committed before you receive it.
Where possible, prioritise expensive debt and avoid taking out additional loans simply to finance festive celebrations. A loan may solve an immediate cash shortage, but create months of repayment pressure.
Strengthen your emergency savings
An emergency fund is one of the most important financial safety nets you can build.
It provides money for unexpected situations such as medical expenses, vehicle repairs, job loss or urgent family needs.
Financial experts commonly recommend saving between three and six months of essential living expenses.
However, if this seems unrealistic, start with a smaller target. Even setting aside E100, E200 or E500 consistently can build a useful financial cushion over time.
Keep emergency savings separate from money intended for shopping, holidays or everyday expenses. The purpose is to have money available when life does not go according to plan.
Review your stokvels, policies and investments
For many emaSwati, stokvels are an important part of financial planning. As payouts arrive, consider whether the money will genuinely improve your financial position.
Instead of spending the entire amount, consider retaining a portion for savings, investing in a small business, purchasing productive assets or settling outstanding debt.
Also review your funeral policies, life insurance, medical aid and retirement contributions.
Check whether premiums are affordable, beneficiaries are correctly recorded and your cover still meets your family’s needs. If you have investments, assess their performance and whether they remain aligned with your long-term goals.
Prepare for the new year’s financial demands
Before January arrives, create a realistic household budget based on your expected income and expenses. Include school-related costs, groceries, transport, utilities, loan repayments, family responsibilities and savings.
Do not forget annual expenses such as insurance renewals, vehicle licensing and maintenance.
These are predictable costs and should ideally be planned for throughout the year rather than treated as emergencies.
If you are self-employed or run a small business, separate personal and business finances and prepare for quieter trading periods.
Ultimately, financial confidence is not determined by how much money you earn but by how deliberately you manage what you have.
You do not need a large salary to begin making better financial decisions. As you prepare to welcome another year, remember that a financially stronger future is built through everyday choices.
Start with what you have, make a realistic plan and give every Lilangeni a purpose.