
Access to finance has long been the Achilles heel of Eswatini’s small and medium enterprises (SMEs). While banks remain cautious lenders, the collateral requirements they impose often exclude the very entrepreneurs who drive innovation and employment. Traditionally, immovable property such as land and buildings had been the gold standard for collateral. Yet, in the kingdom, where land tenure is complex and ownership patterns are restrictive, this model has left many capable business owners and ordinary emaSwati outside the gates of formal credit.
Promise of movable collateral registry
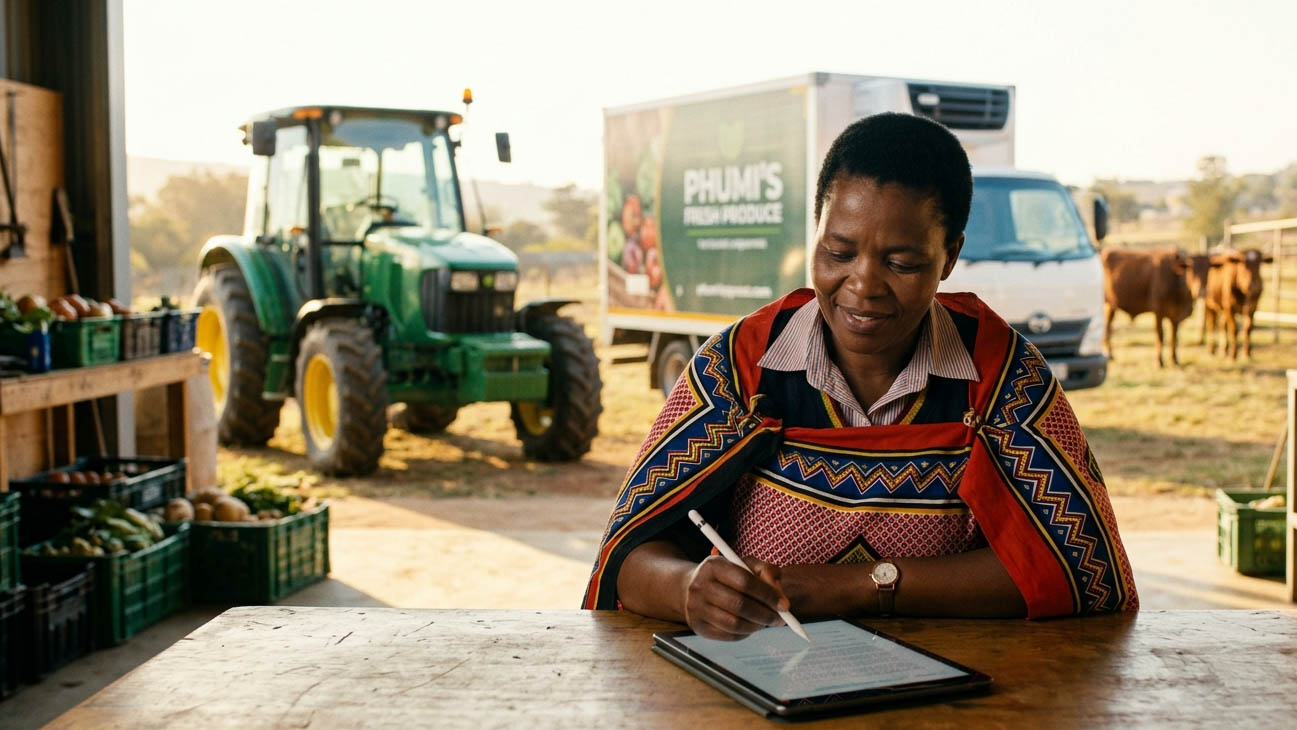
The proposed movable collateral registry, now on the cards, represents a transformative step towards financial inclusion. By allowing movable assets, such as vehicles, equipment, livestock and even future receivables to serve as security for loans, Eswatini aligns itself with global best practice. Countries across Africa, including Ghana, Malawi and Kenya, have already demonstrated how such registries unlock billions in credit for SMEs. At its core, the registry is about trust and transparency. It creates a centralised database where lenders can verify claims on movable assets, reducing the risk of double pledging and fraud. For borrowers, it expands the universe of acceptable collateral, turning dormant assets into active instruments of growth.
Benefits for SMEs, economy
The benefits are multi-layered. First, it strengthens the financial ecosystem by diversifying collateral options, thereby reducing concentration risk in property markets. Second, it enhances credit penetration, enabling banks to reach segments previously deemed ‘unbankable’. Third, it supports economic diversification, as sectors like agriculture and manufacturing, which are asset-rich but cash-poor, gain new leverage. For the economy, it promises a surge in credit availability, particularly for women and youth entrepreneurs who often lack immovable property but own productive assets.
This innovation in the economy will lead to deeper depth of credit, allowing emaSwati access to large sums of credit, which allows for sustained business and fast-tracks economic growth. This will also support the government plan of action to formalise the informal sector. Access to finance is crucial in ensuring access to finance. Also, access to finance for entrepreneurs will be facilitated as self-employed persons are usually unbankable even with proof of account activity. This is because mostly, personal loans are structured for those who are employed, but if movable property is acceptable collateral, there will be deeper depth of credit.
Implementation challenges
However, the registry’s success will hinge on implementation fidelity. A poorly designed system risks becoming another bureaucratic layer rather than a catalyst for growth. Key considerations include legal clarity, where robust legislation must define rights, responsibilities and enforcement mechanisms. Digital infrastructure is equally critical, as a modern, accessible and secure platform will prevent inefficiency and corruption. Capacity building is necessary for both lenders and borrowers, with banks learning to value movable assets accurately and SMEs understanding how to register and leverage their assets. Public awareness campaigns, especially in rural areas, will ensure entrepreneurs know the registry exists and trust its processes.
Eswatini Savings and Development Bank offers a good case study as it used to accept movable property back in the days when we were young. Bankers also need to come to the party and developing innovative products that will be flexible to the depreciation nature of movable assets, ensuring loss minimisation.
Addressing criticisms
Critics may argue that movable assets are volatile and depreciate quickly, making them risky collateral. Yet this is precisely why a registry matters: It provides transparency, valuation standard and legal enforceability. Moreover, movable collateral registries are not meant to replace immovable property but to complement it, broadening the collateral base and democratising access to finance. Through standardised valuations and depreciation standards and methods, banks can come up with the right loan to collateral ratio, ensuring that losses are minimised.
Bold step in financial inclusion
This innovation reflects a recognition that inclusive growth requires innovative tools, not just traditional models. By embracing movable collateral, the kingdom signals to investors, development partners and its own citizens that it is serious about unlocking the potential of its SMEs. The registry also dovetails with regional integration efforts. As the kingdom deepens ties with SADC, COMESA, AfCTA, etc., access to finance becomes a competitive advantage. SMEs that can secure credit against movable assets will be better positioned to scale, export and participate in regional value chains.
Engines of growth
Ultimately, the movable collateral registry is more than a technical reform; it is a statement of intent. It says to the nation’s entrepreneurs: Your assets matter, your ideas matter and your growth matters.
It says to the financial sector: Innovation is not optional, it is imperative. It says to policymakers: Inclusive finance is the cornerstone of sustainable development. As Eswatini prepares to roll out this registry, the challenge will be to ensure that it is not merely a symbolic gesture but a functional, trusted and widely used system. If done right, it could unlock millions in credit, empower thousands of SMEs and mark a decisive step towards a more inclusive economy. The time has come to move beyond immovable walls and embrace the movable engines of growth.


Leave a comment