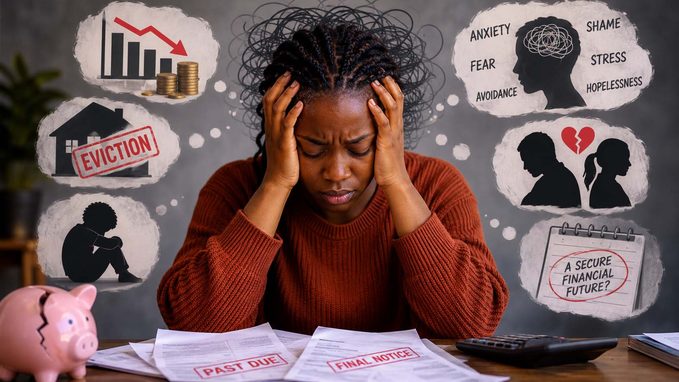
Imagine waking up on the first day of the month to find that your salary account has been decimated before you have even bought a single loaf of bread.
For tens of thousands of emaSwati and beyond, this monthly nightmare is an all-too-familiar reality. Between soaring food prices, escalating electricity tariffs and a relentless sea of direct debits from multiple credit providers, the modern consumer is drowning in a sea of monthly obligations.
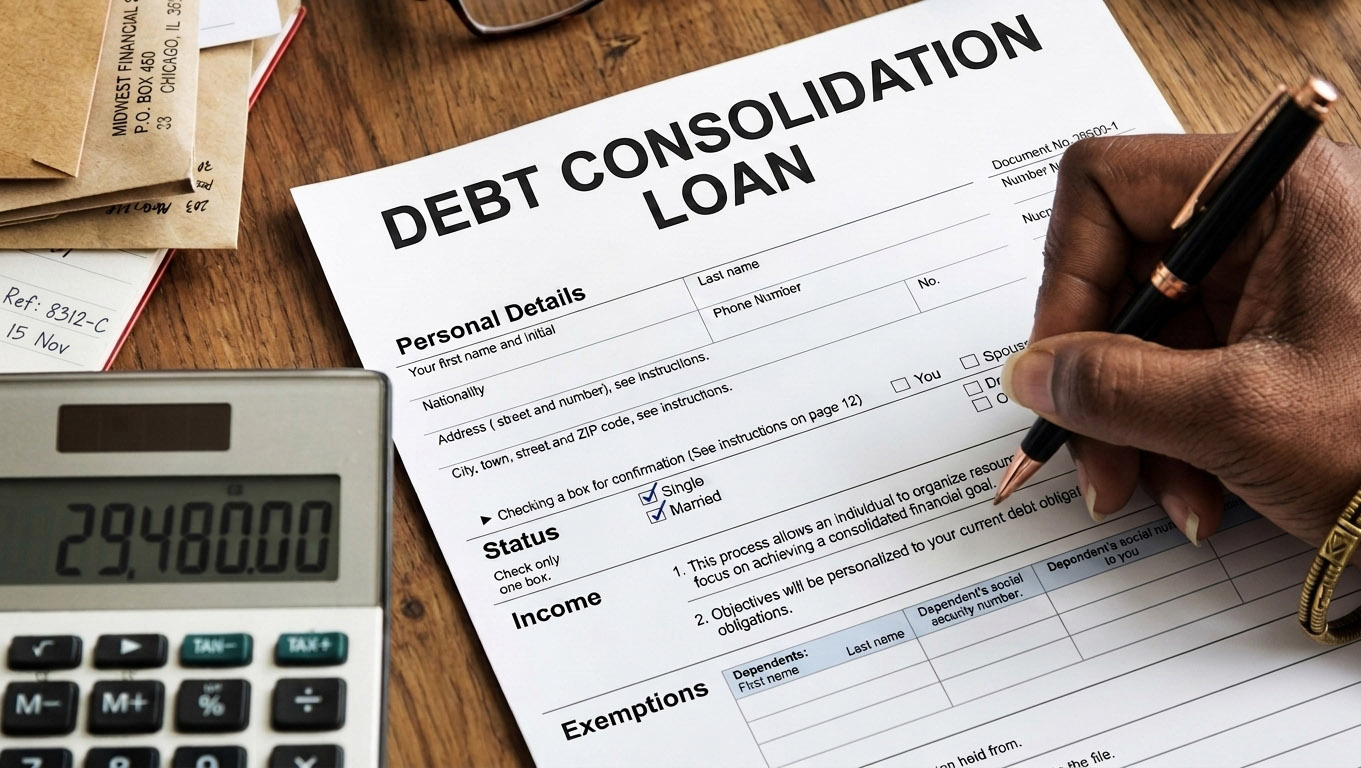
In an attempt to escape this financial stranglehold, an increasing number of consumers are turning towards a remedy promised by banks and microlenders alike: The debt consolidation loan.
Financial advisors have reported that the surge in debt consolidation applications reflected a broader systemic pressure on household income across Eswatini.
They stated that the rising cost of living, exacerbated by stubborn global inflation and regional supply chain pressures, had left many civil servants and private-sector workers relying heavily on microloans, high-interest unsecured credit and store accounts just to bridge the gap between paydays.
According to senior retail banking executives, consumers frequently found themselves managing four or five disparate debts simultaneously.
They explained that attempting to service multiple credit agreements with varying interest rates and administrative fees created enormous psychological and administrative stress.
Consequently, the prospect of combining those debts into a single loan with an extended repayment term often felt like an instant relief valve.
The bankers noted that the appeal was particularly strong among civil servants, whose salaries were frequently burdened by payroll deductions from multiple microfinance institutions, popularly known locally as non-bank financial institutions and microlenders. They observed that consolidation allowed workers to clear immediate, high-interest payroll deductions and restore a portion of their take-home pay.
The hidden cost of breathing room
However, debt experts cautioned that the illusion of financial relief could carry a heavy long-term price tag. Personal finance consultant explained that consolidating multiple short-term debts into a long-term facility often reduced the immediate monthly repayment, but significantly increased the overall interest paid overtime.
She stated that extending a two-year repayment horizon into a five-year or seven-year term meant consumers would ultimately pay far more for their initial debt than originally planned. She highlighted that loan initiation fees, monthly administration charges and mandatory credit life insurance premiums were frequently bundled into the new consolidation package, quietly eroding any potential savings.
Furthermore, financial regulatory observers expressed concern over consumer behaviour following debt consolidation.
They pointed out that many individuals who successfully secured consolidation loans committed the fatal error of keeping their newly freed credit facilities open. They noted that without strict behavioural changes, borrowers quickly accumulated new debts on retail store cards or personal loans, effectively doubling their financial burden and heading towards insolvency.
Evaluate your options
Advisors urged consumers to conduct a rigorous self-assessment before signing any consolidation agreement.
They recommended that consumers first compile a detailed register of all existing obligations, noting the exact interest rates, remaining balances and tenure of each loan.
They advised that consolidation made financial sense only if the interest rate on the new loan was substantially lower than the average weighted interest rate of the existing debts and if the total cost of credit, including all hidden fees, proved lower overall.
Ultimately, industry experts concluded that while a debt consolidation loan could serve as a valuable tool to restructure debt and regain control, it was merely a temporary fix rather than a permanent solution.
They emphasised that unless consumers fundamentally addressed their spending habits and established a strict household budget, taking on a new loan to settle old debts would simply delay an inevitable financial crisis.




Leave a comment